Written By | Staff Writer
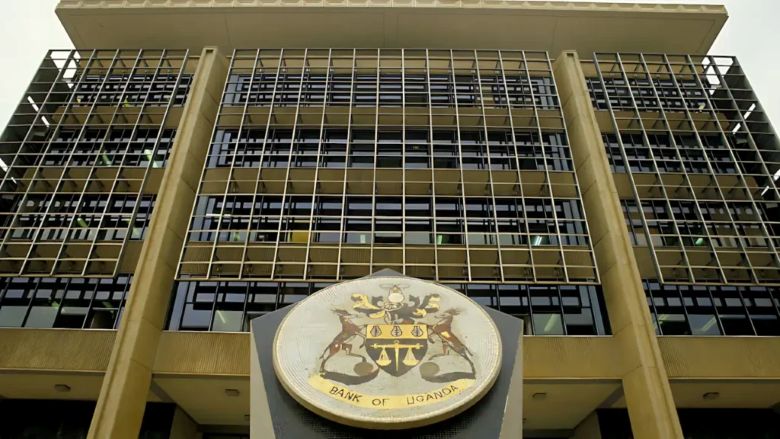
After October’s emergency 225-basis-point hike, the central bank has paused, even as it expects prices to rise sharply over the next year and firms report the gloomiest outlook since early 2023
BUSINESS AND ECONOMY
What happened
The Bank of Uganda (BoU) kept its benchmark Central Bank Rate (CBR) at 12 percent on Monday 9 November, Governor Michael Atingi-Ego announced after the Monetary Policy Committee (MPC) met. The decision follows a rare special meeting on 14 October, when the committee lifted the rate by 225 basis points from 9.75 percent. The Daily Monitor reported that the bank, while holding, warned that inflation is set to rise sharply over the coming year because of higher global oil prices, a weakening shilling and the fallout from the Middle East conflict. Trading Economics noted that the rate is at its highest level since 2017.
The pause lands in a week of weak sentiment data. On Wednesday 4 November the BoU published its Business Tendency Indicator for October, which fell to 53.5 from an upwardly revised 56.7 in September, the lowest reading since February 2023. Business groups had lobbied the central bank ahead of Monday’s decision; the Monitor reported manufacturers warning that another hike would break them, while market participants cautioned that a hold would let inflation run.
How the October shock unfolded
The October hike broke a long period of stability. The BoU had left the CBR at 9.75 percent since October 2024, and at its regular August meeting on 13 August it held for what Trading Economics counted as the eighth consecutive time, saying inflationary pressures remained relatively contained. By mid-October that assessment had changed. The central bank blamed escalating conflict in the Middle East for a sharp deterioration since August, which pushed up international oil prices and shipping costs and added pressure on the shilling. “The resulting depreciation, together with elevated international oil prices, has raised domestic fuel pump prices,” the bank said in its October statement. Uganda has no oil refinery and imports its fuel, so those costs pass quickly into transport and food prices.
The Reuters-reported emergency meeting on 14 October produced the largest single policy-rate adjustment since October 2011, according to Nairametrics, and took the rate to its highest since December 2016 by that outlet’s count. Trading Economics reported, citing its sources, that the bank had proposed using part of Uganda’s roughly $6 billion in foreign reserves to ease dollar shortages but that President Museveni opposed the idea over concerns about importers; that claim comes from a single aggregator and was not independently confirmed here. The shilling was trading at around 4,130 per US dollar at the open on 14 October and closed near 3,951, according to BoU mid-rates cited by the Rio Times.
What the latest data show
Inflation has begun to react. The Uganda Bureau of Statistics reported on 30 October that annual inflation rose to 5.8 percent in October, with food-crop prices up 10.7 percent. The central bank has previously treated 5 percent as its inflation target, and the Daily Monitor’s coverage of the 9 November decision stressed its forecast that inflation will climb significantly from here.
The business-confidence survey shows where the strain is concentrated. According to the Rio Times’ breakdown of the BoU data, construction sank to 39.8 from 46.0, with order books at 30.3, and wholesale trade slipped to 46.7 from 49.2; both are below the 50 line that separates optimism from pessimism. Firms’ assessment of their own finances dropped to 47.1 from 52.6, current employment fell to 47.9, and access to credit scored just 38.9, the weakest of the economy-wide indicators. The selling-price index rose to 66.4 from 61.5, which may reflect firms passing on higher costs. Not everything is weak: agriculture edged up to 57.5, financial services remain the most upbeat sector at 77.7, and the survey’s three-month outlook scored 59.2, suggesting more firms expect conditions to improve than to worsen. The survey itself gives no reasons for the decline, so linking it to the rate rise is an interpretation.
The BoU has also cut its growth forecast for the year to June 2027 to between 6.0 and 6.5 percent from 7.0 to 7.5 percent, according to the same Rio Times account. The Monitor reported that medium-term growth is still projected to strengthen, averaging about 8 percent over five years, supported by private investment, exports, oil-sector developments and the government’s Tenfold Growth Strategy, the plan to expand the economy to $500 billion by 2040.
Who is affected and why it matters
The central bank’s dilemma is stark: higher rates defend the shilling and anchor inflation expectations, but they raise borrowing costs for firms and households when credit access is already poor. A Daily Monitor analysis titled “Defending the shilling creates costly trade-offs” made that point, arguing the government must support the currency without choking off investment and growth. Borrowers, particularly in construction and trade, face repayments that stay high well after October’s jolt. Savers and holders of government paper benefit from higher yields, and a stronger shilling helps importers of fuel and inputs.
There was some relief on the currency. The Monitor reported that the shilling appreciated by about 5 percent during the first four trading days of the week before the decision, reaching around Shs4,040 buying and Shs4,050 selling per dollar, on rising dollar inflows. Export earnings are one source of support: Africanews reported on 22 October that August export revenue was up 36 percent on higher gold earnings. Whether those inflows persist will matter as much as the policy rate for the shilling’s path.
What to watch next
The key variable is oil and the Middle East. The Rio Times points to a calmer region or lower world oil prices as the most direct route to easing pressure on fuel and the shilling; the opposite would keep inflation rising and could force further tightening. Watch November’s inflation print from the statistics bureau, which will show how fast pass-through is moving, and the next business-confidence reading, whose release date has not been confirmed. The BoU lists 3 December for its next monthly trade data. A second consecutive month of sub-54 confidence, or a deterioration in construction and wholesale, would strengthen calls from business for relief, while a firmer shilling would give the MPC room to stay on hold. It is not yet clear whether October marks a low point or the start of a longer slide.