BUSINESS
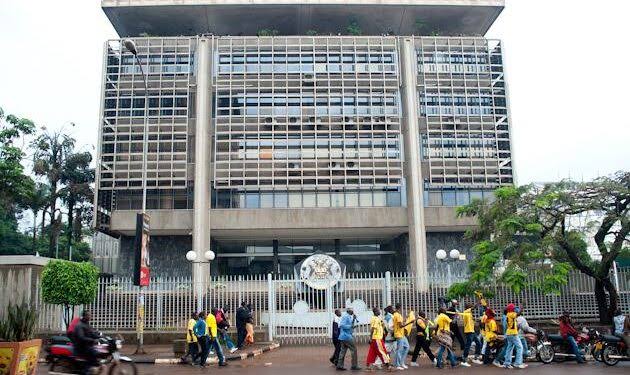
With just over a month left before the Bank of Uganda's September 30 deadline, only seven of an estimated 90 large Savings and Credit Cooperative Societies (SACCOs) have secured the licences that will bring them under direct central bank supervision — a slow crawl that is exposing deep anxiety inside a cooperative movement that hundreds of thousands of Ugandan farmers depend on to save, borrow and survive the lean seasons.
The figures, disclosed this week by State Minister for Finance in charge of Microfinance, Shartsi Kutesa Musherure, show 15 more applications in the pipeline, but that still leaves roughly 68 eligible SACCOs — institutions holding some of the largest pools of members' savings in the country — with just weeks to complete a licensing process many say they are not ready for.
For Uganda's farmers, this is not a distant regulatory footnote. SACCOs are the financial backbone of rural production: the institutions that hold seed-capital savings before planting season, that extend the small loans for fertiliser, sprayers and school fees, and that increasingly serve as the last-mile channel for government programmes such as the Parish Development Model (PDM), which routes subsidised credit to farming households through cooperative structures. When a large SACCO wobbles, it is often a farming community's collective nest egg that is at risk.

Shartsi Musherure
A regime born of past collapses
The new supervisory framework, created under the Microfinance Deposit-Taking Institutions Act and the accompanying MDI (Registered Societies) Regulations of 2023, targets SACCOs whose voluntary savings exceed Shs1.5 billion and whose institutional capital tops Shs500 million. Those thresholds capture the country's biggest cooperative savings institutions — the ones capable, if mismanaged, of triggering losses large enough to shake public confidence in the wider financial system.
That risk is not theoretical. Uganda's cooperative movement, born in 1931 to protect farmers from exploitative colonial-era trading monopolies over cotton and coffee, has weathered repeated waves of collapse — from the disintegration of the Uganda Cooperative Central Union and the Cooperative Bank during the economic turmoil of 1979–2006, to a more recent and quieter crisis among savings groups. Of 385 registered teachers' SACCOs nationwide, only 39 remain operational today, according to sector data — a collapse rate that has left civil servants, traders and farmers alike newly wary of where they park their savings. In one widely reported case, Parish Development Model beneficiaries using a mobile savings app lost more than Shs30 million from a group SACCO account in Kaliro District after funds vanished before members could withdraw them.
It is against that backdrop that Bank of Uganda officials argue self-regulation within the cooperative movement is no longer sufficient. "If a large SACCO with billions in savings collapses, it can trigger widespread financial panic and destabilise the broader financial sector," Aomu Mackay, the central bank's Director of Non-Bank Financial Institutions, said this week.
Under the new arrangement, qualifying SACCOs migrate out of the loosely supervised Tier Four microfinance category — overseen by the Ministry of Finance's Microfinance Regulation Department — and into the Bank of Uganda's direct supervisory net, alongside commercial banks and other deposit-taking institutions. The shift brings with it tougher governance and financial-management requirements, mandatory reporting, and access to a Deposit Protection Fund and centralised credit referencing designed to catch fraud and over-indebtedness before they metastasise.
Farmers caught between protection and cost
The reform is not without resistance, and the pushback illuminates a genuine tension for farming communities. Cooperative leaders argue that layering bank-style regulation onto community-owned savings groups risks pricing ordinary members out of the very services that make SACCOs valuable in the first place.
Ivan Asiimwe, Executive Director of the Uganda Cooperative Alliance, warned that the compliance costs associated with central bank supervision mirror those imposed on commercial banks — a burden that smaller, farmer-heavy SACCOs may struggle to absorb. "It also takes away the unique form of financial inclusion SACCOs provide as community-based initiatives and turns them into commercial and profit-oriented entities," he said.
The Uganda Co-operative Savings and Credit Union has gone further, formally opposing full central bank licensing for large SACCOs on the grounds that it duplicates oversight already provided under the Cooperative Societies Act, administered by the Ministry of Trade, Industry and Cooperatives. Its chief executive, Sylvester Ndiroramukama, has called instead for a single, tailored regulatory framework built specifically for the cooperative sector rather than one borrowed wholesale from commercial banking.
These are not abstract objections for the farming households who rely on SACCOs precisely because they are cheaper and more accessible than commercial banks. A poultry or coffee farmer in a rural sub-county typically cannot meet a commercial bank's collateral and documentation requirements, but has built years of trust with a community-based SACCO whose loan officers know the rhythms of the local growing season. If licensing costs push those SACCOs to raise fees, tighten lending criteria, or in the worst case shut down rather than absorb new compliance costs, the very farmers the reform is meant to protect could lose access to affordable rural finance altogether.
A model of what compliance can deliver
Yet the Bank of Uganda points to early adopters as evidence the transition can be navigated. Mbarara-based EBO Financial SACCO became the first institution in the country's history to obtain a Bank of Uganda licence, in March this year, and has since expanded to seven branches across western Uganda's farming districts.
"We are the first SACCO in the history of Uganda to obtain this licence from the Bank of Uganda, and our reason for this is to ensure that we protect our members' deposits, build their confidence and enable financial inclusion," said Julian Tumusiime, the SACCO's Executive Director, adding that central bank oversight had strengthened governance and boosted member confidence enough to support expansion rather than contraction.

Why the deadline keeps slipping
This is not the first deadline the sector has missed. The Bank of Uganda originally set March 31, 2026 as the cut-off, then extended it to September 30 to give SACCOs more time to assemble documentation and allow the central bank to conduct nationwide stakeholder sensitisation. With just seven licences issued and 15 applications still in review out of an estimated 90 eligible institutions, the pace suggests many SACCOs are still grappling with basic readiness — governance structures, audited financial statements, and capital verification — rather than simply awaiting paperwork approval.
The central bank has been explicit that failure to apply by September 30 could carry legal penalties, including closure, for eligible SACCOs that do not come forward. At the same time, regulators have instructed banks and other regulated financial institutions not to cut off services to eligible SACCOs during the transition window, an acknowledgment that abrupt disruption could ripple through to the farmer-members who depend on those institutions for day-to-day financial services.
What is at stake for the wider agricultural economy
Cooperative finance sits at the intersection of two of the government's biggest agricultural priorities: expanding the Parish Development Model's reach into rural savings and credit, and channelling billions of shillings in agro-industrialisation financing — through vehicles like the Uganda Development Bank and the EIB-Centenary credit line — down to smallholder level. SACCOs are frequently the last link in that chain, the local institution that actually disburses money to a farmer's account or collects group savings ahead of the planting season.
A cooperative sector under-supervised enough to collapse, or over-regulated enough to become unaffordable, both represent a threat to that pipeline. The next five weeks will determine which of the two risks the Bank of Uganda's reform ultimately manages to avoid — and for the estimated tens of thousands of rural savers whose money sits inside the roughly 68 SACCOs still without a licence, the outcome is far from academic.
Minister Kutesa has pledged the government's support for what she described as a regulatory approach that protects members' money while preserving the cooperative, community-owned character of SACCOs — a balance cooperative leaders say has yet to be demonstrated in practice, and one Uganda's farmers will be watching closely as the September 30 deadline draws near.
Published By | Business News Editor