Agriculture
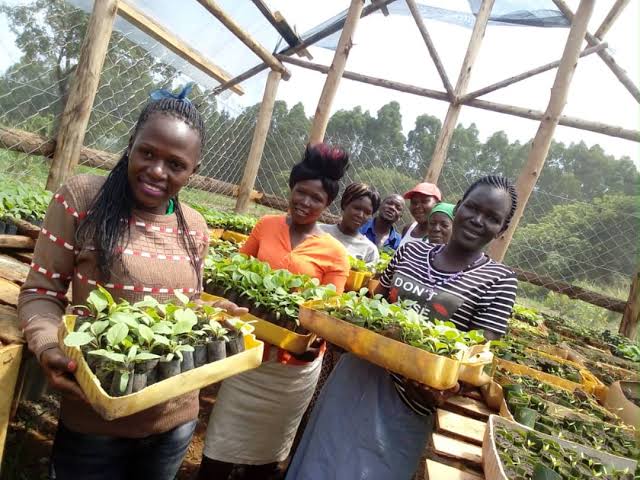
For thousands of women farming small plots in Uganda's refugee settlements and the host communities around them, a failed harvest or a sudden hospital bill has traditionally meant one grim set of choices: sell the goats, borrow at punishing interest, or pull a child out of school. This week, a pilot launched in Kampala set out to rewrite that equation, using a technology more associated with cryptocurrency speculation than smallholder agriculture.
Women's World Banking, the global network focused on financial inclusion for women, announced a partnership with Ripple, the blockchain payments company, to test a stablecoin-enabled insurance product for roughly 3,000 women smallholder farmers in Uganda. The initiative, called “Harnessing Stablecoins for Women's Financial Resilience in Uganda,” uses Ripple's US dollar-backed stablecoin, RLUSD, as the settlement engine behind an insurance policy that promises to pay out within hours of a verified shock — not months, as is typical with conventional insurance or humanitarian aid in rural Uganda.
The mechanics: parametric insurance meets blockchain
The model combines two ideas that, until recently, rarely intersected. The first is parametric insurance, in which a payout is triggered automatically by an objective measure — rainfall falling below a set threshold, for instance, or a verified health event — rather than by an adjuster assessing an individual's losses on the ground. The second is blockchain settlement, which allows the underlying funds to move instantly and transparently between institutions.
RLUSD sits on the back end of the transaction, moving value between the insurer and the payment system. But the women receiving the money never interact with the stablecoin directly. When a predefined shock occurs, the system converts the payout into Uganda shillings and deposits it into a beneficiary's mobile money account — the channel most rural Ugandan women already use for everyday transactions. “As we continue exploring how stablecoins like RLUSD can support new real-world use cases, we're excited to partner with Women's World Banking,” said Jonathan Perri, Ripple's Director of Social Impact. “This pilot demonstrates how the programmability of RLUSD can help automate insurance payouts for farmers in Uganda when predefined conditions are met, improving speed and efficiency.”
To design and deliver the product on the ground, Women's World Banking is working with Pula, an insurtech firm with experience building agricultural insurance products across Africa, along with humanitarian organisations already active in Uganda's refugee and host communities. The pilot will run in northern Uganda's refugee settlements and surrounding host districts, areas where displacement and climate stress compound each other.

Why speed matters more than the sum
Uganda's exposure to climate shocks has intensified in recent years. Droughts and floods have grown more frequent, and between 2018 and 2020 alone, climate-related disasters displaced an estimated 334,000 people across the country. For subsistence farmers, and women in particular, the damage from a single bad season rarely ends with the season itself. Households without savings, credit or insurance to fall back on are often forced to liquidate productive assets — a dairy cow, a plot of seed stock, tools — just to survive, undermining years of accumulated progress in a matter of weeks.
Women's World Banking's global research puts a number on the scale of the problem: more than 800 million women worldwide have no reliable way to receive relief payments after a climate emergency. In Uganda, where the vast majority of rural women depend on rain-fed agriculture with little buffer against risk, that gap translates directly into stalled farms, interrupted school fees and deepening debt cycles.
“Women farmers are already managing thin margins,” said Stephen Ambore, Policy Director for Africa at Women's World Banking. “A single shock, such as a failed harvest or a health emergency, can erase years of progress. Financial resilience powers economic empowerment. When payouts arrive in hours instead of months, women can absorb shocks without selling assets or taking on debt, allowing them to stay invested in their farms, businesses, and families and continue building long-term financial security.”
A test with three goals
The pilot is explicitly designed as a proof of concept rather than a mass rollout. Organisers have set out three things they want to demonstrate. First, that predictable, shock-responsive support — covering agricultural, health and life risks — can reach women who currently have no access to insurance at all. Second, that stablecoin-backed settlement can meaningfully cut payout times and increase transparency compared with both conventional insurance and humanitarian cash transfers. Third, that the model generates enough real-world evidence to justify scaling it beyond Uganda to other contexts facing similar climate and displacement pressures.
To measure whether faster money actually changes behaviour, researchers will track outcomes using Women's World Banking's Economic Empowerment Barometer, looking at whether women can cope with shocks without resorting to distress asset sales, whether their confidence in financial decision-making improves, and whether their control over household resources increases.
What it means for Uganda's wider farm-finance gap
The pilot lands against the backdrop of a well-documented credit squeeze in Uganda's agricultural sector, where formal lenders have tightened conditions and average lending rates for farmers remain among the highest of any sector in the economy. Micro-insurance products for smallholders have historically struggled to reach scale in Uganda partly because manual claims processing makes them too costly to administer at the premiums rural households can afford. By removing that manual layer, the partners behind this pilot are betting they can lower overheads enough to make coverage viable for women who would otherwise be priced out entirely.
There are real limits to what 3,000 policies can prove. The number is a rounding error against Uganda's millions of smallholder households, and questions remain about how the model would be funded and regulated at scale — stablecoin regulation in East Africa is still evolving, and humanitarian financing of this kind often depends on donor cycles that can be difficult to sustain. Whether mobile money operators, insurers and regulators can align quickly enough to take a successful pilot to a national product is an open question the partners have not yet answered publicly.
Still, the logic driving the experiment is grounded in a problem Uganda's farmers know intimately. In refugee settlements in the north and in host communities nearby, where a dry spell can wipe out a season's maize or a bout of malaria can drain a family's savings overnight, the gap between when a shock hits and when help arrives is often the difference between a family that recovers and one that doesn't. If the model proves it can close that gap reliably and cheaply, its backers argue it could be adapted for other recurring crises — flooding in Kasese, drought in Karamoja, or health emergencies in settlements elsewhere in the country. For the roughly 3,000 women in the pilot, the near-term promise is simpler: when the next shock comes, they may not have to choose between feeding their families today and keeping the farm they are building for tomorrow.
Published By | Features Editor